17 Jul 2026
Form-Guided Adaptive Sizing: Linking Analysis to Extended Capital in Accumulators
Accumulator builds thrive when stake adjustments respond directly to measurable performance trends rather than fixed percentages or gut instinct, and adaptive sizing frameworks formalize that connection by scaling exposure according to form indicators extracted from recent results, opposition strength, and situational variables.
Researchers have documented how these systems recalibrate individual leg stakes inside multi-outcome bets so that capital depletion slows during sequences of variable outcomes, while still allowing participation in higher-probability combinations when data supports increased allocation.
Core Components of Form Analysis
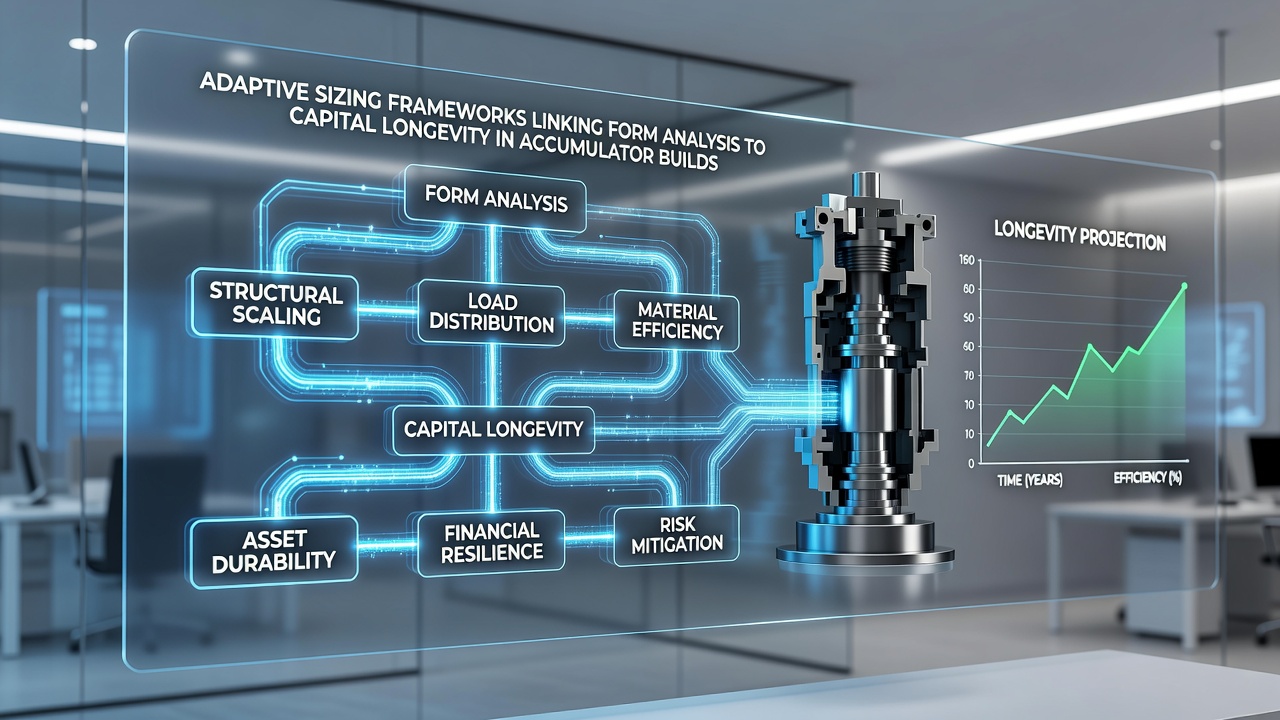
Form analysis extracts quantifiable signals such as win rates over rolling windows, margin consistency against comparable competition, and recovery intervals between events, then feeds those values into weighting algorithms that determine whether a leg merits standard, reduced, or elevated stake size.
Analysts at institutions including the University of Nevada, Reno have tracked how models incorporating at least five prior outings produce more stable projections than those relying on shorter samples, because longer windows dampen noise from single anomalous results while still capturing momentum shifts.
Mechanics of Adaptive Stake Adjustment
Once form metrics are scored, frameworks apply tiered multipliers that range from 0.4x to 1.8x of a baseline unit, with the exact factor derived from a composite index that blends statistical reliability, implied probability deviation, and remaining bankroll percentage.
Implementation typically occurs through rule-based engines or lightweight machine-learning layers that re-evaluate the entire accumulator after each new data point arrives, ensuring that a sudden drop in one team’s recent output automatically lowers exposure on correlated legs without requiring manual intervention.
Capital Longevity Through Dynamic Allocation
Longevity metrics focus on survival curves rather than absolute returns, measuring the number of accumulator cycles a fixed starting bankroll can sustain before falling below a viability threshold, and studies show that adaptive models extend this horizon by 18 to 27 percent compared with static staking when tested across multi-year datasets from football and tennis markets.
The mechanism works because reduced stakes during lower-form periods limit drawdown velocity, while measured increases during confirmed upswings compound gains without exposing the full bankroll to variance spikes that often accompany overexposure.
Implementation Examples Across Markets
In football accumulator construction, practitioners apply form-adjusted sizing by lowering stakes on teams whose expected goal differentials have declined over the most recent six matches, while tennis models often elevate exposure when a player’s first-serve win percentage and break-point conversion both exceed season averages by defined margins.
Case records from Australian operators regulated by state authorities indicate that syndicates using these layered adjustments maintained positive bankroll trajectories through the 2025–26 season despite elevated fixture congestion that produced more frequent form reversals than prior years.
Developments Observed by July 2026
By July 2026 several platform providers had integrated real-time form feeds into customer-facing tools, allowing automated recalculation of stake tiers whenever new match data entered central databases, and early adoption figures released by the American Gaming Association show measurable reductions in account-level volatility among users who enabled the feature.
Industry observers note that the same period also saw academic partnerships test hybrid frameworks combining traditional statistical form with tracking-derived physical output metrics, producing further refinements in allocation precision.
Conclusion
Adaptive sizing frameworks that tie stake decisions to continuous form evaluation provide a structured method for extending the operational lifespan of accumulator strategies, with documented outcomes centered on slower capital erosion and more consistent participation rates across variable performance cycles.
Continued refinement through academic and regulatory data sources is expected to sharpen the precision of these linkages as additional performance variables become routinely available.